
When you sell your HDB flat, the selling price is not necessarily the amount of cash you will receive.
If you used CPF savings to buy the flat or service your housing loan, part of the sale proceeds must first be refunded to your CPF accounts.
Understanding this early can help you estimate how much cash you may actually have available for your next home.
How Much CPF Do You Need to Refund?
According to CPF Board, the amount you generally need to refund is:
CPF principal amount used + accrued interest
Importantly, this is not a fixed percentage of your selling price.
The amount depends on the actual CPF dollars withdrawn for your property over time and the accrued interest on those withdrawals.
You can check your exact estimated refund through the “What Happens If” section of your CPF Home ownership dashboard.
What About CPF Housing Grants?
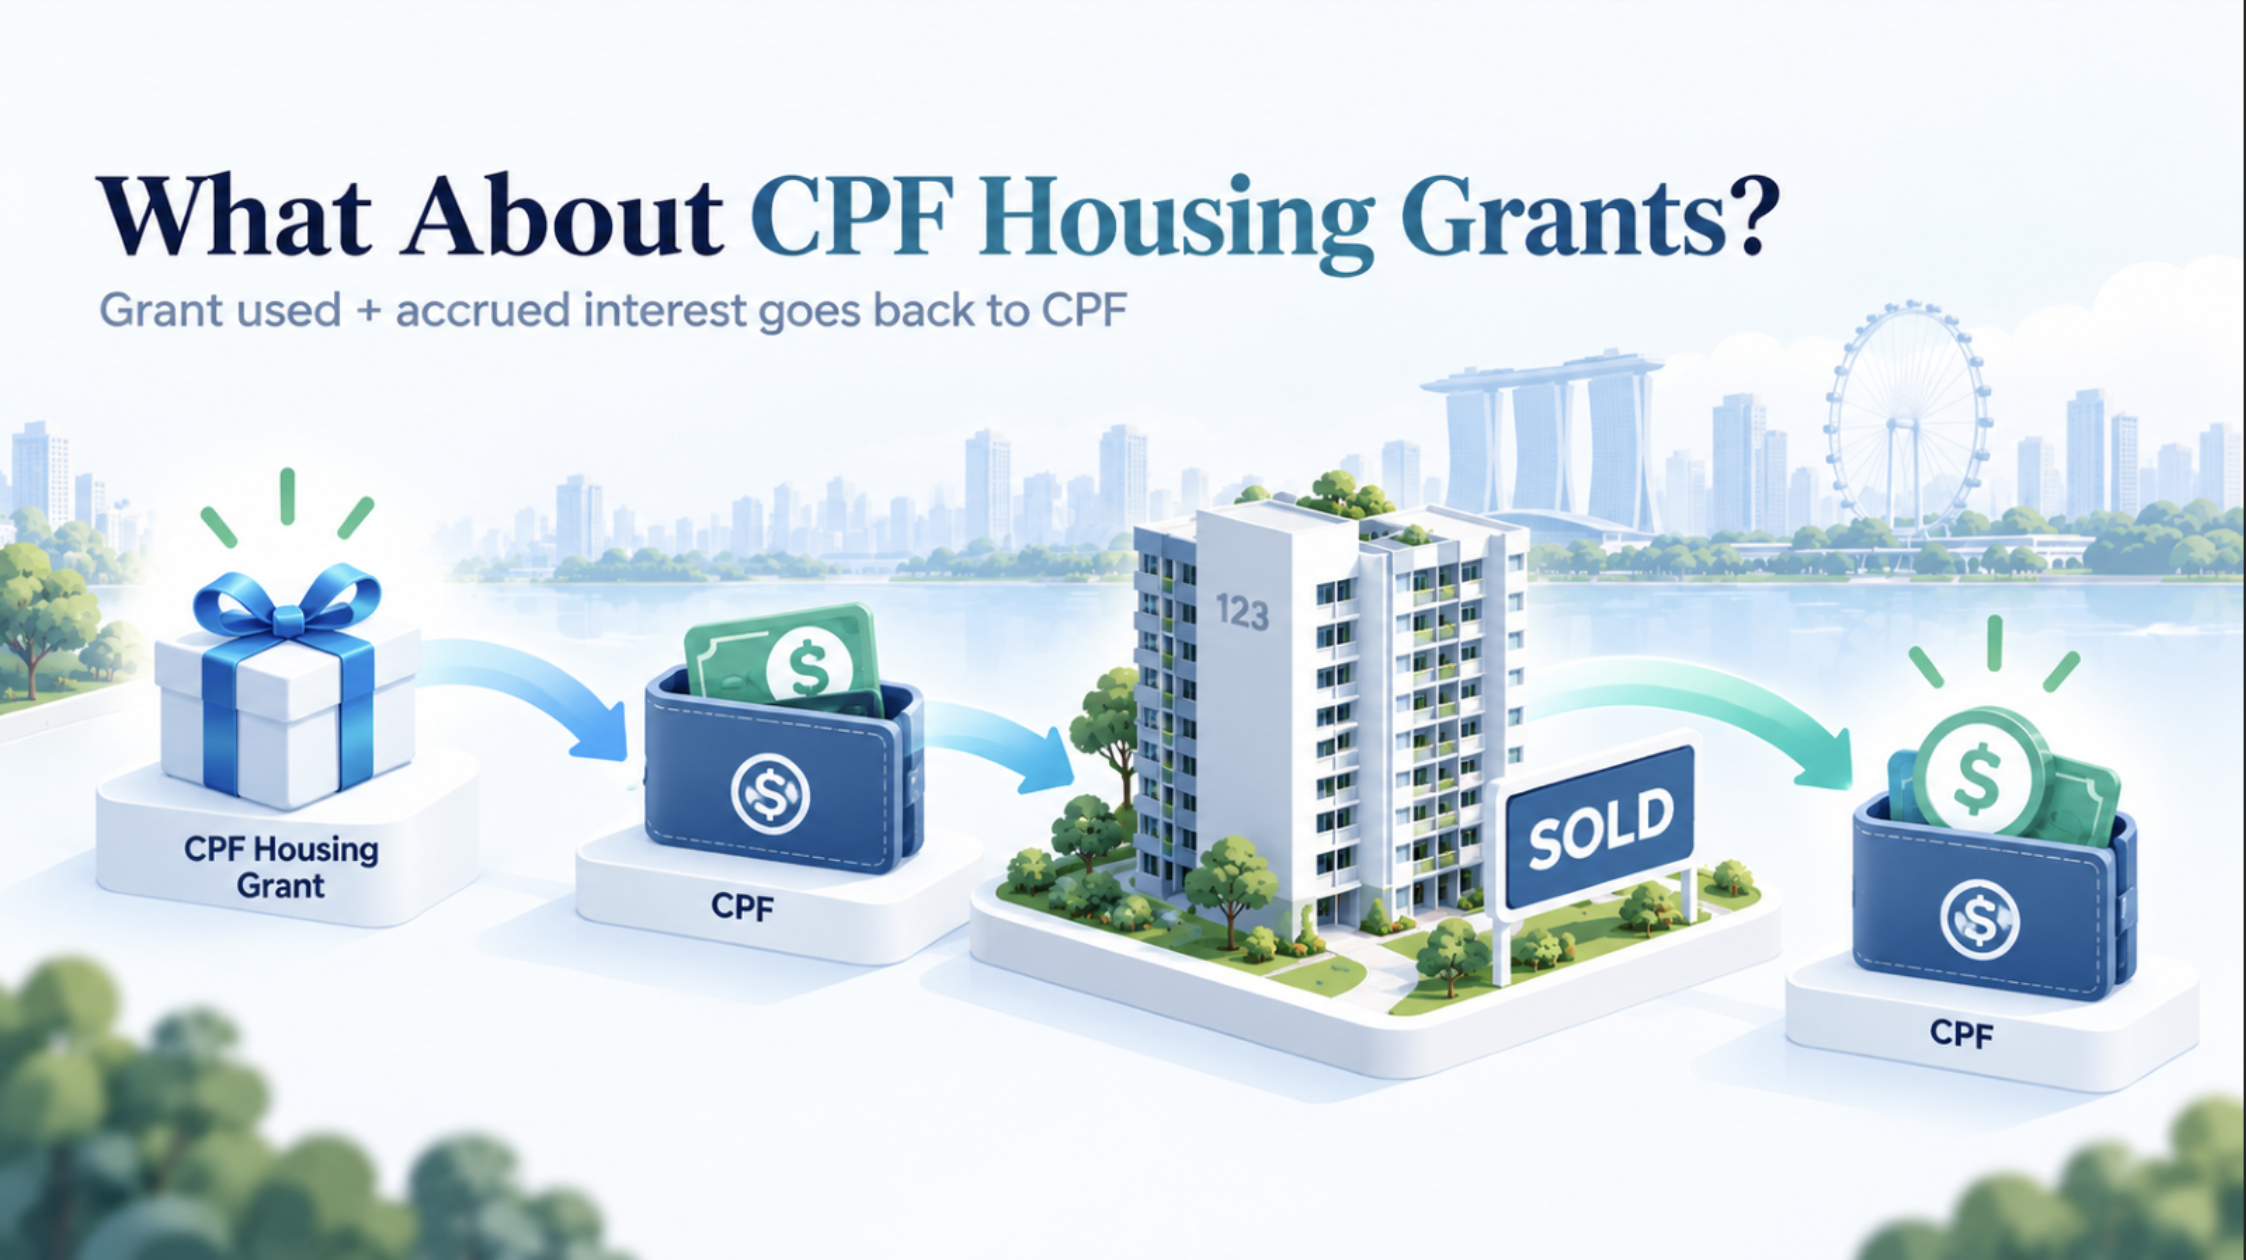
CPF housing grants used for your property form part of the CPF principal amount withdrawn.
Housing grants are generally credited to your CPF Ordinary Account and used towards the purchase of the property. When you sell, the amount of housing grant used — together with its accrued interest — is included in your required CPF housing refund.
In other words, you are not returning the grant to HDB. The refund goes back into your CPF accounts.
CPF Board explains the treatment of housing grants here.
For members who received more than S$30,000 in housing grants, part of the refunded grant may be allocated to other CPF accounts, depending on prevailing CPF rules.
What Is Accrued Interest?
Accrued interest is the interest your CPF savings would have earned if they had remained in your Ordinary Account instead of being used for your property.
CPF OA savings currently earn a base interest rate of 2.5% per annum, so the longer CPF savings are used for housing, the larger the accrued interest component can become.
Because CPF may have been withdrawn at different times for the down payment and monthly mortgage instalments, the refund is a cumulative calculation based on your actual withdrawals, rather than a simple percentage of the property price.
This is why two owners selling flats for the same amount can have very different CPF refund requirements.
Where Does Your Selling Price Go?
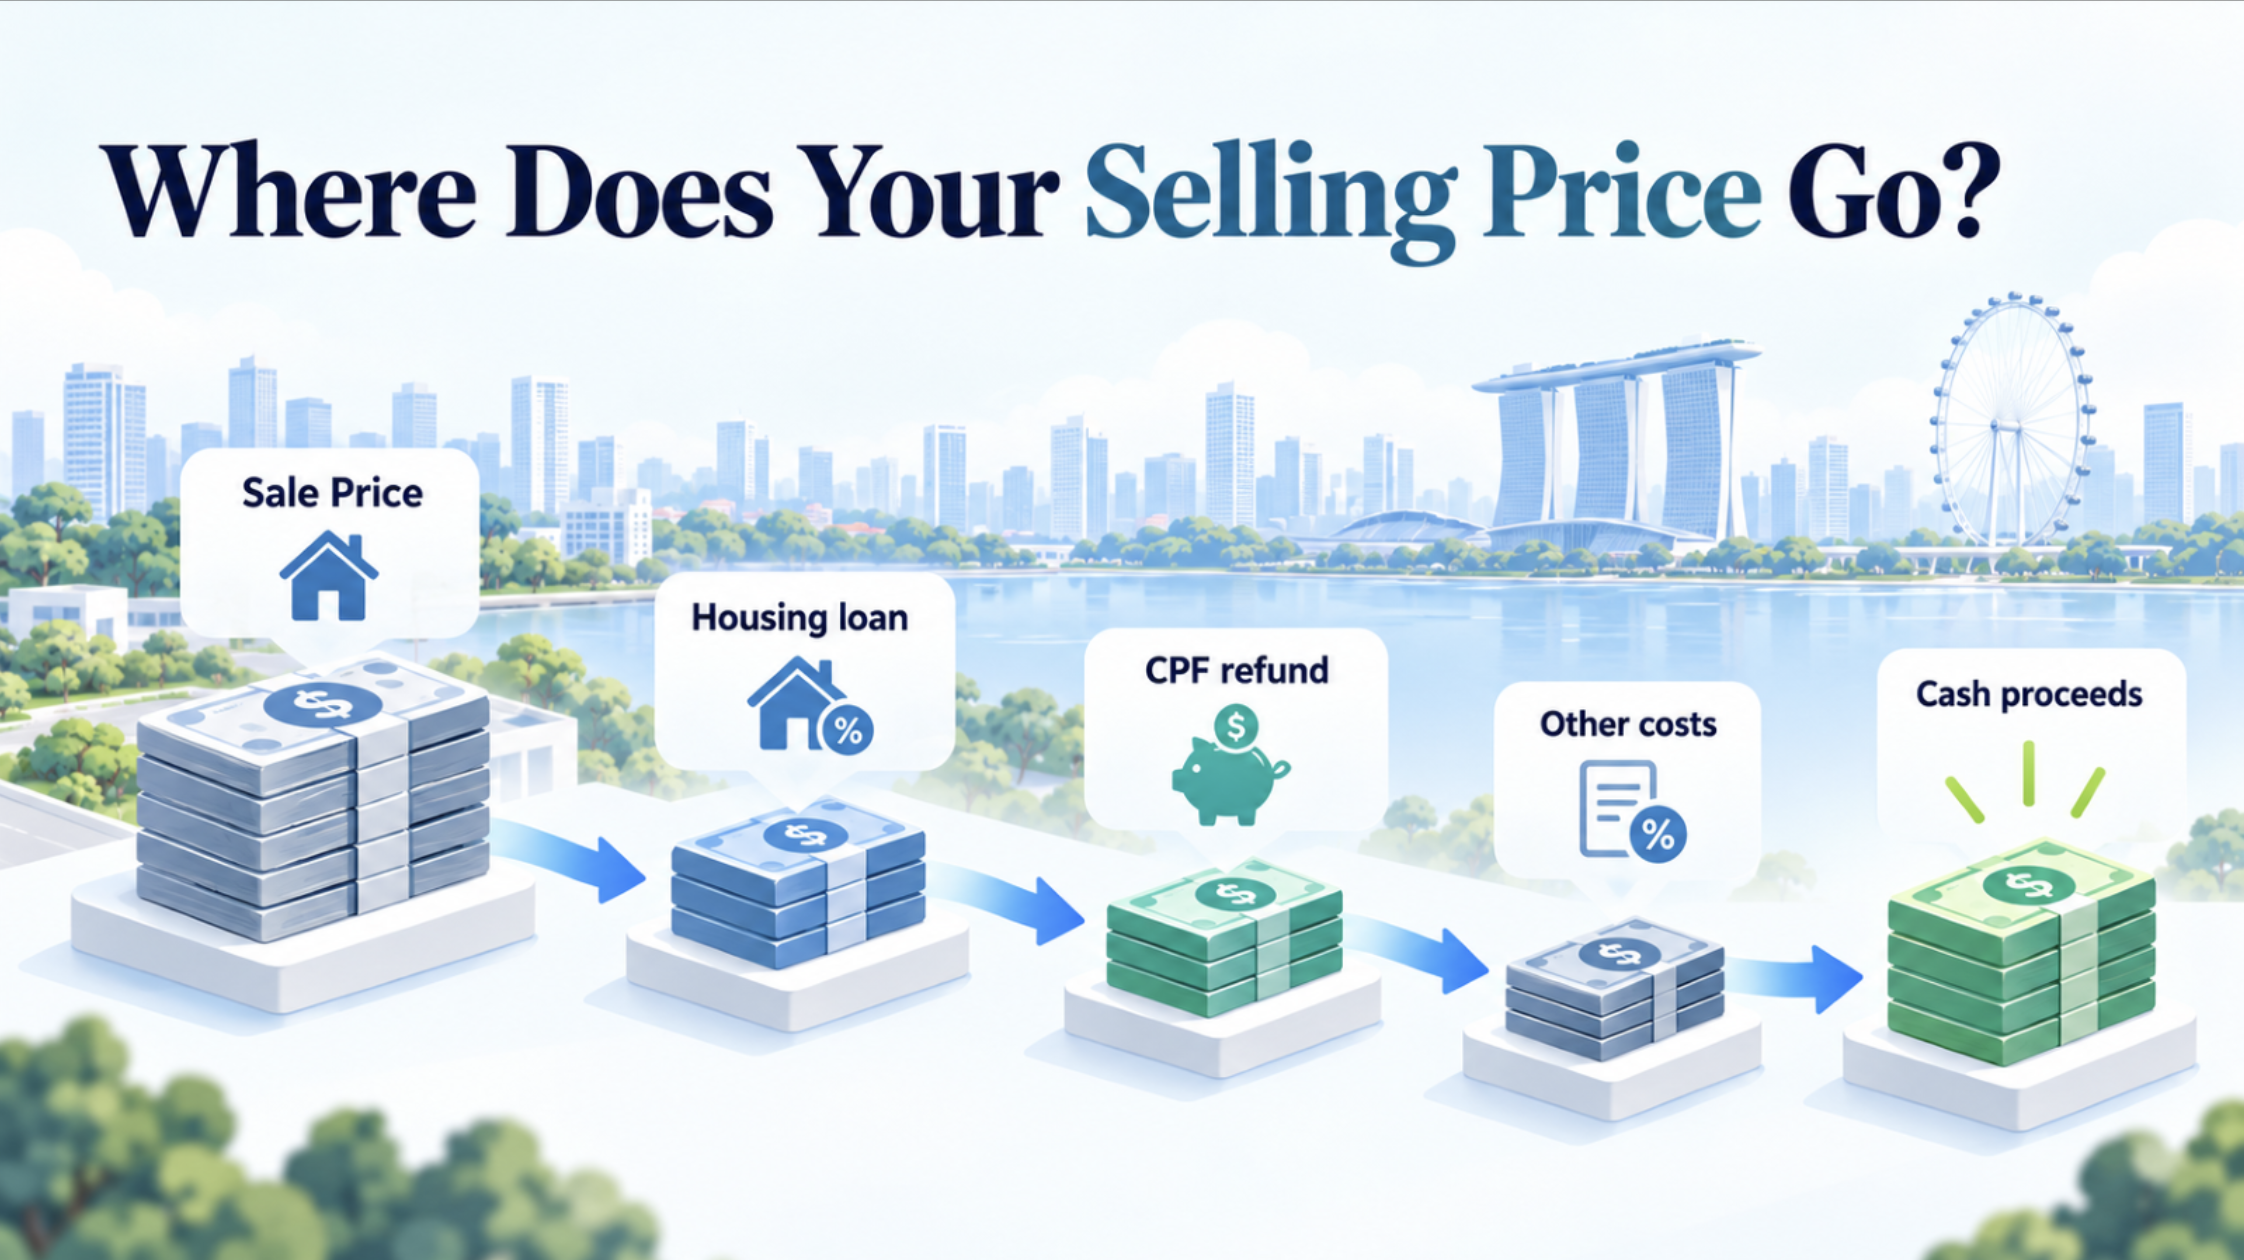
When you sell, the proceeds are generally used in this order:
1. Repay your outstanding housing loan
2. Make the required CPF housing refund
3. Settle other applicable selling expenses
Whatever remains becomes your cash sale proceeds.
So if your flat sells for S$700,000, you should not assume you will receive S$700,000 — or even most of it — in cash.
What If You Are 55 or Older?
Age also affects what happens after the CPF refund is made.
If you are below 55, your housing refund is generally credited to your Ordinary Account (OA).
If you are 55 or older, the refund will first be used to top up your Retirement Account (RA) to your applicable retirement sum, with the remaining balance generally staying in your OA.
You can read more in CPF Board’s guide to selling a home before and after age 55.
If you previously pledged the property to meet your retirement sum, additional refund requirements may also apply.
What If the Sale Proceeds Are Not Enough?
If you sell your property at market value and the proceeds are not enough to cover both the outstanding housing loan and your full CPF refund, you generally do not need to top up the shortfall in cash.
Instead, the remaining sale proceeds after paying the housing loan are refunded to CPF.
Option monies received from the buyer are considered part of the selling price and may also need to be included in the CPF refund.
Check Your Numbers Before Listing
Before selling, it helps to understand both:
How much your flat may sell for
and
How much of that amount may actually remain as cash
RealValue Instant Valuation can provide an initial property valuation reference, while RealInsight can help you review recent transactions before deciding on an asking price.*
For the CPF side, always check your actual required refund through your CPF Home ownership dashboard.
The Bottom Line
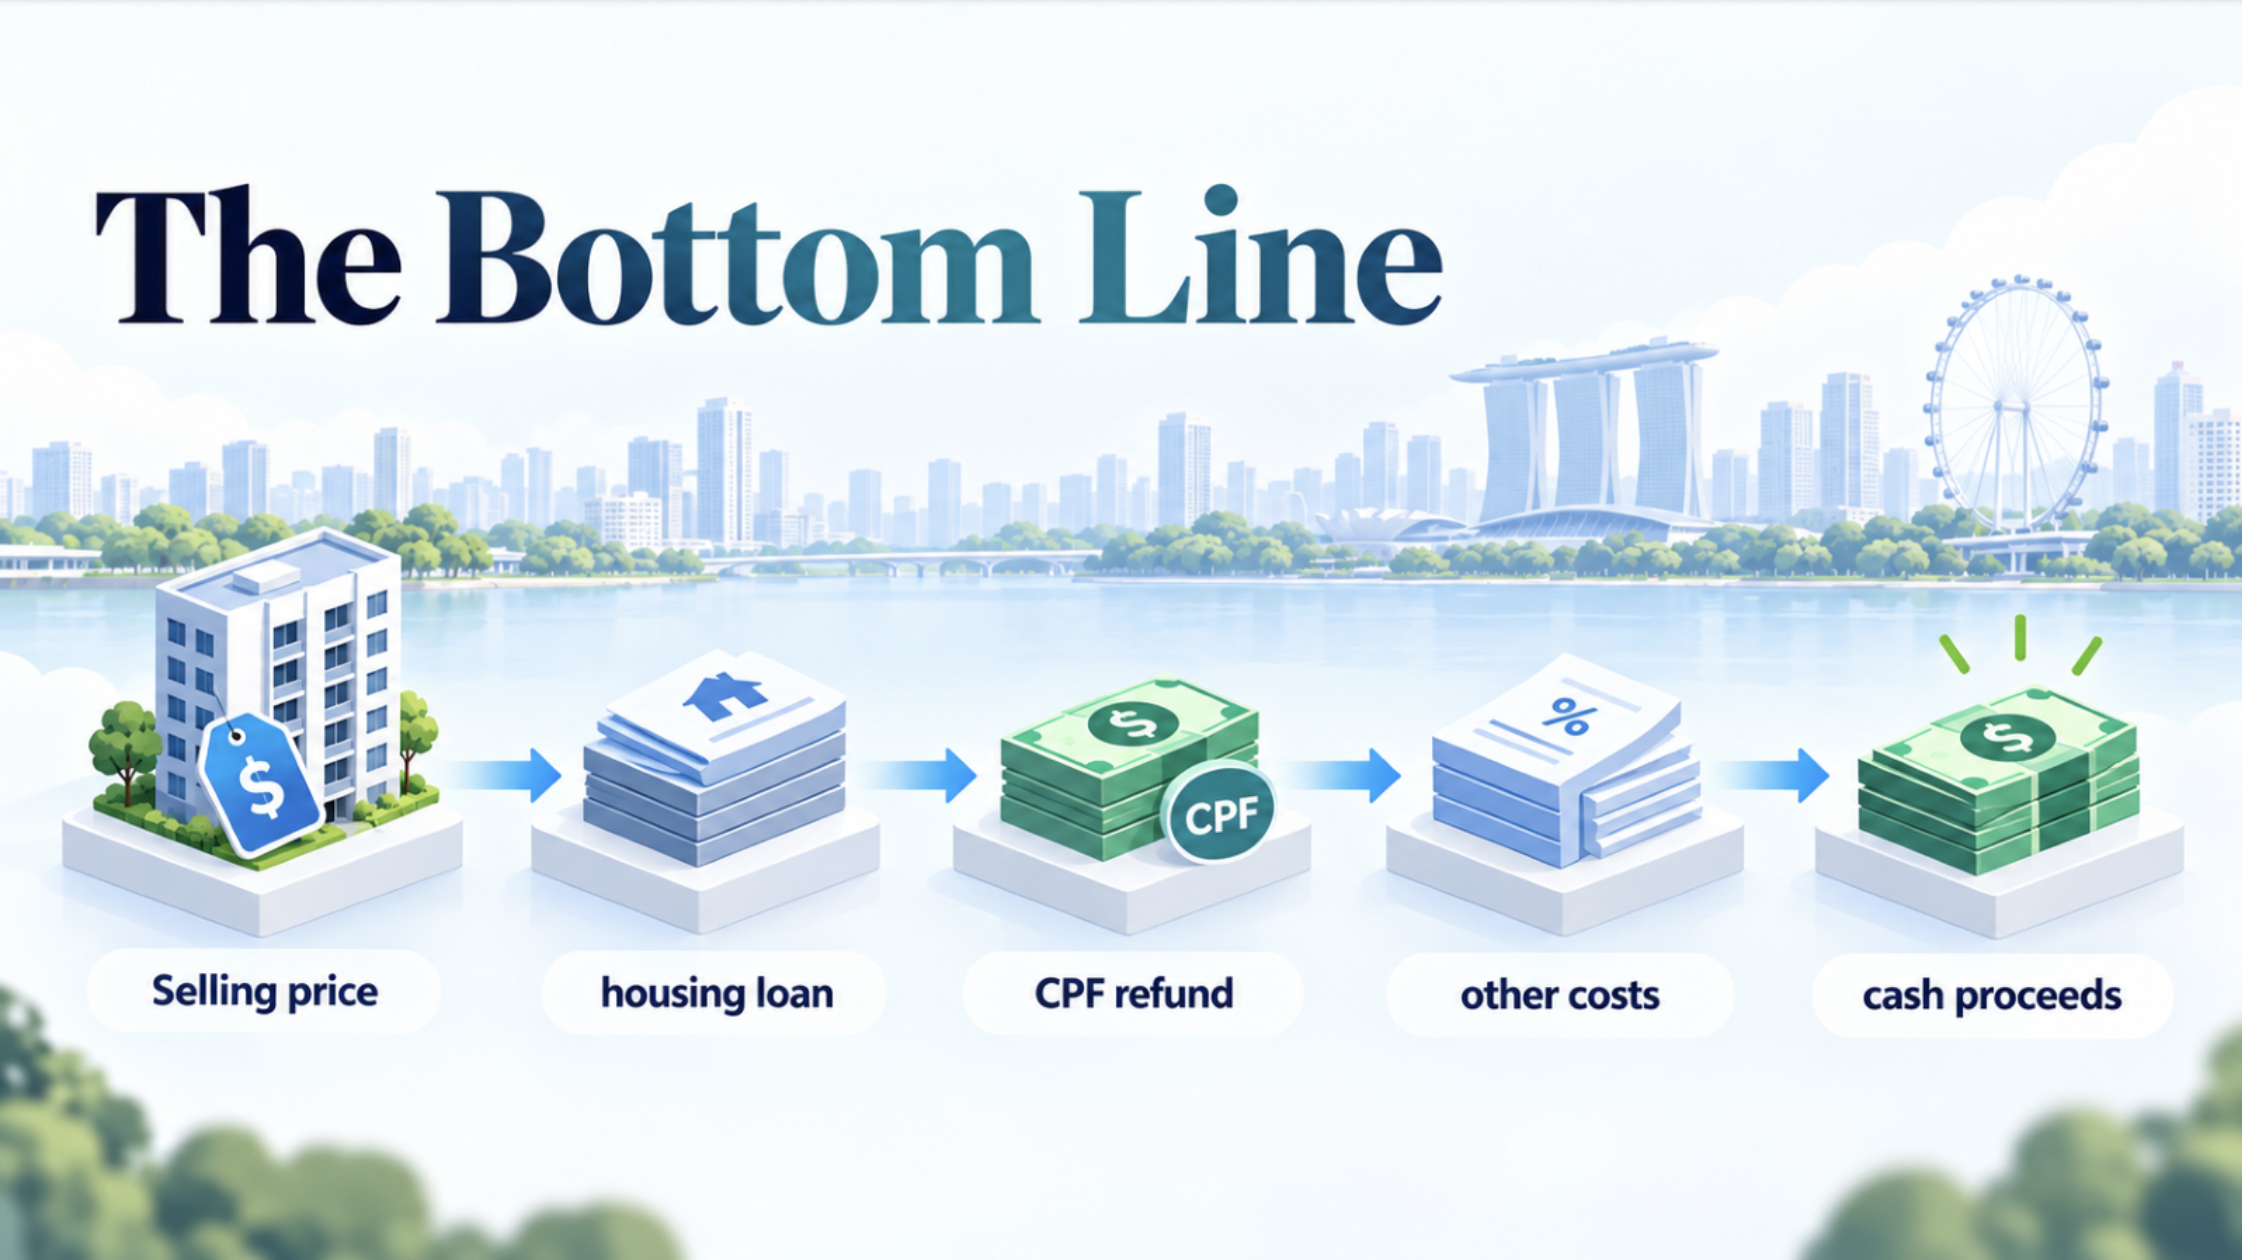
When selling an HDB flat, think of the money in this order:
Selling price → outstanding housing loan → CPF principal + accrued interest → other costs → cash proceeds
Your CPF refund is not a fixed percentage of the selling price. It depends on how much CPF you actually used, when you used it, and the accrued interest that built up over time.
Knowing these numbers early can help you plan your next property purchase more accurately.
Disclaimer: CPF and HDB rules used in this article are accurate as of 29 October 2026 and may change. Always refer to the latest CPF housing refund guidance before committing to a property sale.
Share this article


